When I started checking the data for this article, We expected finances to play a large role in the 2026 survey. The results also point to a separate motive: many Americans want work to remain part of their retirement years.
A closer look at the survey reveals two different motives: the need for income and the wish to remain active.
According to the 2026 Planning & Progress Study, 50% of millennials and the same share of Gen X expect to work during their retirement years or are already doing so. A year earlier, 45% of millennials and 48% of Gen X gave that answer.
Half of a generation is a large enough number to make us ask what has actually changed.
Finances are a major part of the answer. Among respondents who plan to work during retirement, 47% say they will need the income to fund their retirement. Among Gen X, that figure rises to 51%. On the other hand, 56% of all respondents in the same group say they want to remain active and mentally engaged.
We would be cautious about calling every plan to work in retirement a response to inadequate savings. The survey also identifies personal and social reasons.
Let us see why these generations lack confidence in Social Security.
Are Politics and the Future of Social Security Changing the Way People Plan for Retirement?
There is no good evidence that partisan politics alone explains why half of Gen X and millennials expect to work in retirement.
There is, however, clear concern about the decisions the federal government will have to make about the programs retirees rely on.
The 2026 Retirement Confidence Survey, conducted by the Employee Benefit Research Institute and Greenwald Research, shows that 78% of workers are concerned that the U.S. government will make significant changes to the current retirement system. Among current retirees, 69% report the same concern.
Under those projections, the program will not “run out of money” in 2032. Payroll tax revenue will continue to come in. The problem is that under current law, that revenue would not be enough to pay full scheduled OASI benefits once the reserves are depleted. Congress can change revenue, benefits, or other rules before that point.
For a worker who is 45 or 50 years old, a projection like that changes the psychology of retirement planning. If you do not know what the rules will look like in ten or twenty years, extra income through work can easily become another layer of protection in a personal budget.
Boomers Entered One System, Gen X Another, and Millennials Are Planning for a Third
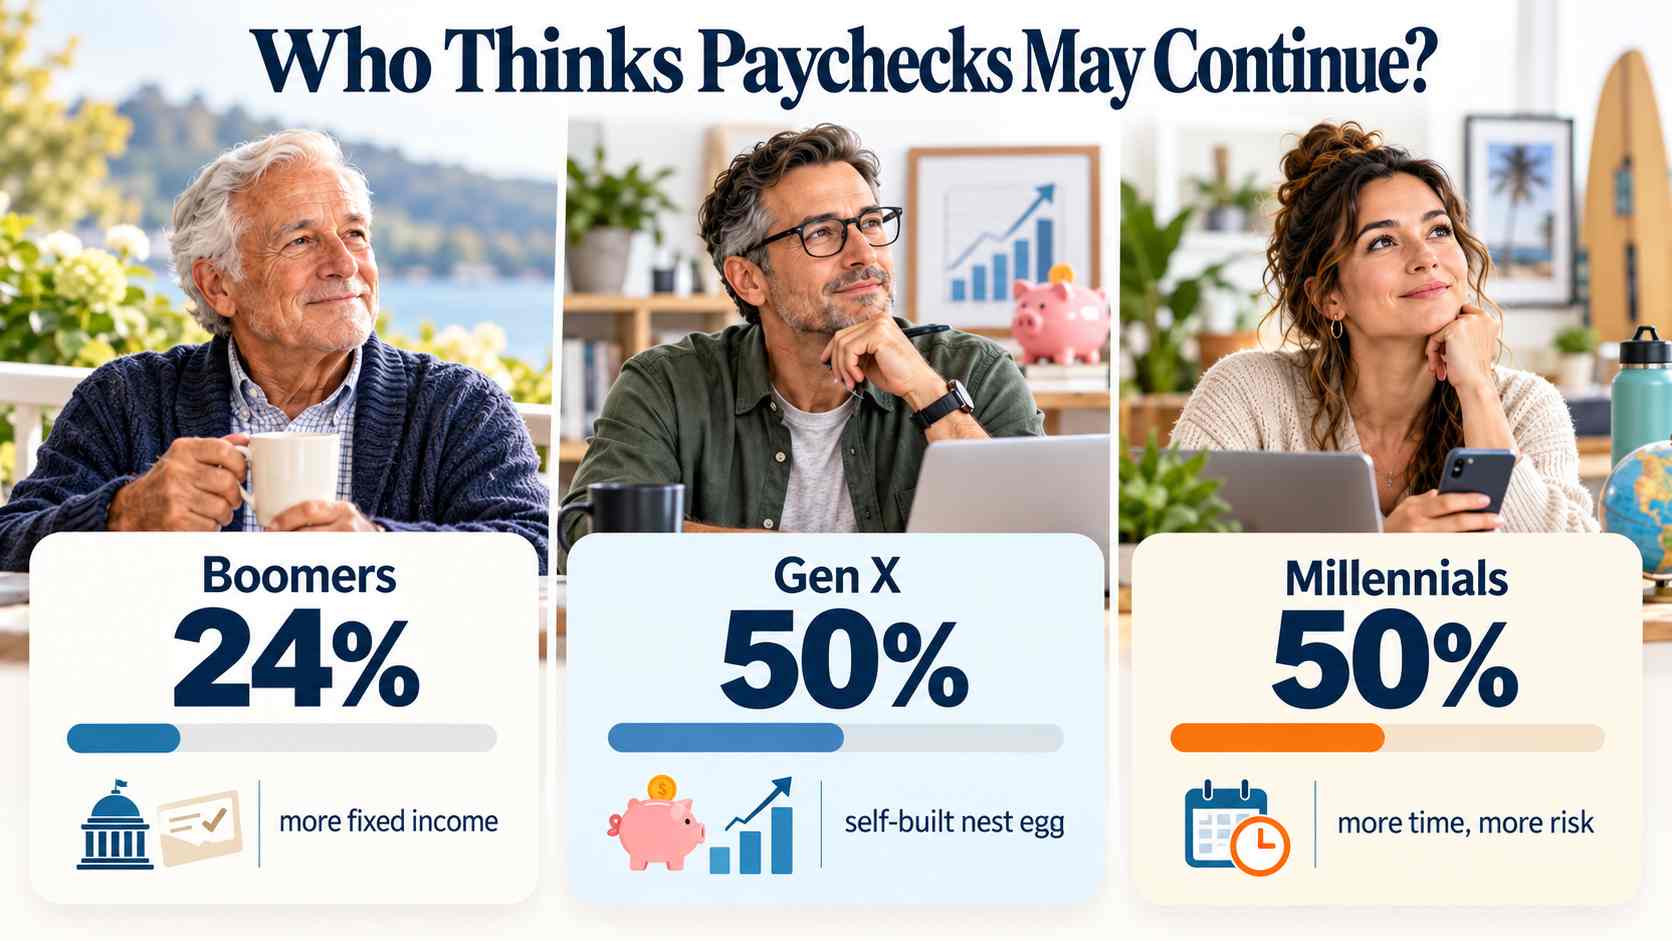
A generational comparison may best explain why the figure for work in retirement differs so much between older and younger Americans.
Let us look at the numbers.
| Generation | Expects or already has work in retirement | What retirement looks like for them |
| Boomers | 24% | Greater reliance on Social Security and historically greater access to traditional pensions |
| Gen X | 50% | First generation to spend most of its career after the shift toward the 401(k) model |
| Millennials | 50% | Earlier start to retirement savings, but a longer time horizon and greater reliance on personal savings and future work |
With a traditional pension, the employer promises a certain level of income under the rules of the plan. With a 401(k), much more of the final outcome depends on employee contributions, investment returns, and the length of time spent saving.
Gen X found itself almost exactly on that historical dividing line.
A NIRS analysis of Gen X households found median private retirement savings of about $40,000. Only 14% of members of the generation in the analyzed data had a defined benefit plan. About 55% participated in an employer-sponsored retirement plan.
Millennials have a different advantage: time.
Northwestern Mutual finds that they started saving for retirement at an average age of 28. Gen X started at 32. Millennials expect to retire at around 64, and Gen X at around 67.
Still, a longer savings period is not the same as security. As many as 55% of millennials in the same survey believe there is a possibility that they will outlive their savings. Among Gen X, 50% give that answer.
Because of that, the same word, retirement, no longer describes the same financial model for all three generations.
What Workers Expect and What Retirees Actually Do Are Not the Same Story
We found a useful reality check in the TIAA data: the age people expect to stop work can differ substantially from the age at which current retirees actually left.
A TIAA Institute study published in July 2026 found a five-year gap between the average age at which current retirees actually left the workforce and the age at which future retirees expect to do so. Current retirees in the sample stopped working at an average age of 57. Future retirees expect to stop at 62.
Even more notable, about half of people who are still planning for retirement already believe they may have to delay it.
Why do people leave work earlier than planned?
There is no single reason. Another TIAA study shows that health shocks can significantly reduce the likelihood of working into older age. The analysis includes serious health conditions and a decline in overall health status.
That is the biggest weakness in a plan that depends on future earnings.
You can control how much you save today. You cannot control with the same degree of certainty what your health will look like at 68 or what demand will exist for your occupation.
Questions Worth Asking About the Retirement Data
After we compared the surveys, a few practical questions remained:
Will Social Security Stop Existing in 2032?
No.
The official projection for the OASI trust fund shows that reserves under the intermediate scenario could be depleted in the fourth quarter of 2032. Ongoing revenue would then cover about 78% of scheduled OASI benefits if the law remained unchanged.
Are Boomers in a Better Retirement Position Simply Because They Saved More?
It would not be justified to draw that conclusion.
The generations worked under different retirement systems. Older workers had greater exposure to traditional pensions, and Gen X spent a much larger share of its career in a system based on individual accounts such as 401(k)s.
Does Continuing to Work Automatically Solve a Retirement Savings Shortfall?
No.
The effect depends on earnings, expenses, and the amount that can actually remain available for savings. A longer working life also depends on health and job availability.
What Happens to Your Budget if Work Ends Before 65 or Soon After?
Test your budget twice: once with expected work income and once without it. Essential expenses should not depend on a paycheck you may be unable to earn later.
If basic expenses can still be covered by Social Security, retirement savings, and other stable sources, future work serves as additional support. If the budget immediately becomes unsustainable without employment income, future work is not an addition to the plan. It is one of its main assumptions.
Working in Retirement Says Something Bigger About How American Retirement Has Changed
So, will these generations actually be able to work for that long?
Research on current retirees suggests that the question should not be answered casually.
Our suggested stress test is straightforward: calculate how long your retirement resources would last if your final paycheck arrived several years earlier than expected.
That is a much stricter test.
And a much more useful one.