Medicare Part B in 2026 costs $202.90 per month, the annual deductible is $283, and a home you own still comes with property taxes and occasional major repairs. A large withdrawal from a traditional IRA can increase taxable income, while helping an adult child with $500 per month adds up to another $6,000 over the course of a year.
Once everything is put on paper, retirement can quickly look very different from the picture someone imagines several years earlier. That is also confirmed by the 2026 Retirement Confidence Survey, in which 41% of retirees said their total expenses during retirement were higher than they had expected before leaving work.
When I started reviewing the data, We began with the 2026 Retirement Confidence Survey and found a broader issue than medical bills alone. Familiar household expenses often cost more in retirement than people anticipated. Medical bills are a major part of the story, but it turns out they are not the biggest one.
If you do not have time to read the whole article but the topic interests you, here are the most important points:
- 41% of retirees say their retirement expenses are higher than they expected.
- Medicare, home maintenance, and major healthcare bills can put significant pressure on a budget.
- Large withdrawals from IRA and 401(k) accounts can increase taxes and Medicare premiums.
- Helping children and grandchildren can quickly become a serious annual expense.
- The biggest surprises often come from familiar expenses that were not included properly before retirement.
Medicare Costs Go Beyond the Standard Part B Premium
The standard Part B premium gives only the starting figure for a healthcare budget. Some services come with coinsurance, while dental care, hearing aids, and long-term help with daily activities can bring separate bills.
During 2026, Fidelity estimated that a person retiring at age 65 could spend about $185,000 on healthcare over the rest of their life. The estimate covers a long period and individual differences, but it gives a good sense of the size of a category that many people reduce to a monthly premium before retirement, and we have covered this topic before.
Paying Off the Mortgage Is Great, but It Does Not End Home Costs
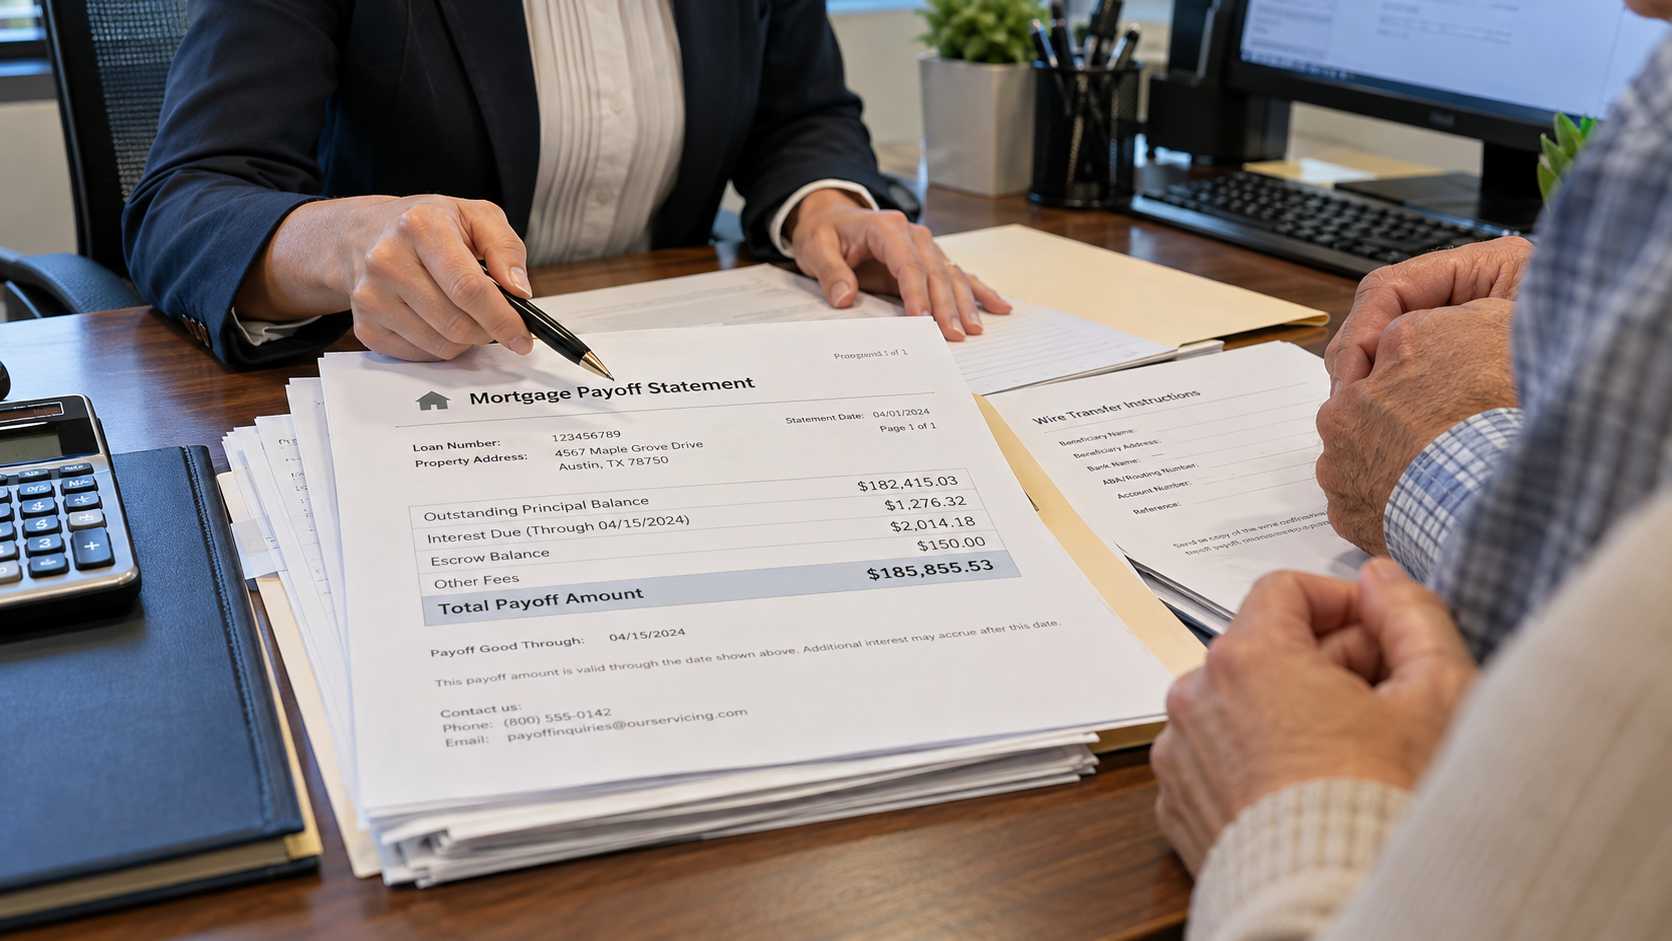
The final mortgage payment can free up a large part of monthly income. After that, property taxes, insurance, maintenance, and major repairs that appear over the years still remain.
Financial advisers often use a framework of about 1% of the home’s value per year for maintenance. For a property worth $400,000, that comes to about $4,000 annually. The actual figure depends on the age of the property and local labor costs, so that percentage serves as a starting reserve.
Later, the budget may also include services the homeowner once handled personally, such as yard work or heavier seasonal jobs. For a retirement budget, We recommend a separate annual home-maintenance allowance. Property taxes, repairs, and paid help can continue long after the mortgage ends.
A Large IRA Withdrawal Can Cost You Dearly
The balance in a traditional 401(k) or IRA can easily look like money ready to spend, but withdrawing that money becomes part of the tax calculation.
For most owners of traditional retirement accounts, the IRS sets the start of required minimum distributions at age 73, and withdrawn amounts generally count as taxable income.
Imagine an $80,000 renovation paid entirely from a traditional IRA. The renovation itself still costs $80,000, but annual taxable income can then be significantly higher. The extra income can also affect Medicare premiums through IRMAA rules.
For a major purchase, compare two numbers: the price you pay and the additional tax that a retirement-account withdrawal may create.
Helping Adult Children Can Become a Regular Retirement Expense
Family support rarely looks large when calculated monthly. An amount of $500 seems manageable, but over four years it becomes $24,000.
The same applies to helping grandchildren with education or contributing toward a first home purchase. Such decisions can have great personal value, and a retirement plan becomes clearer when each one has an annual limit.
Give family support its own annual limit in your budget. A small monthly contribution can become a substantial long-term obligation. That makes it immediately clear how much room remains for personal expenses and how long the same level of support can continue.
Inflation Is Nobody’s Friend!
Social Security COLA gives one percentage for all beneficiaries, while every household has its own expense structure. One person may spend a larger share on housing, another on healthcare.
We would compare the actual change in your annual bills with the general inflation rate. Your personal budget may tell a different story.
If home insurance rises by $600 per year and other regular expenses increase by a few hundred dollars more, the combined change shows how much disposable income has actually changed.
What Other Problems Can Retirees Face?
EBRI research points to another retirement challenge: some households spend down their assets slowly even when they have room for greater current expenses.
The practical question for a retiree is how much to reserve for later years and how much can reasonably support life today.
A Practical Budget Check Before Retirement
Start with annual costs that do not appear every month. Reserve funds for home repairs and health expenses, check the tax effects of large withdrawals, and decide how much family support your budget can sustain.
The amount left after those costs is a more useful estimate of the money available for everyday life.
The central lesson in the research is to attach realistic annual costs to familiar expenses before the final paycheck arrives. The biggest surprises in retirement often come from familiar categories that still have not been given a realistic annual figure before the final paycheck.