Over the past few months, we looked at the renewed debate over Social Security COLA after the 2027 increase was confirmed. The central issue remains the same: a national adjustment cannot reflect every retiree’s expenses.. Organizations that represent older Americans are calling for changes to the way it is calculated, and the confirmed 2027 increase has renewed the broader debate over how Congress should change Social Security.
Most of the story still comes down to one percentage. For 2026, COLA was 2.8%, which gave the average retired worker about $56 more per month.
On October 14, 2026, the Social Security Administration announced a 3.6% COLA for 2027, which will raise the average retirement benefit by about $75 per month beginning in January 2027.
We compared the 2026 increase with the costs that retirees face. A more useful question soon emerged: enough for whom?
To examine that gap, we turned to a survey of 2,000 Social Security recipients. Their answers offer a measure of perceived financial pressure, not a direct audit of each household’s expenses.
Here are the survey results that stood out in our review:
- 54% of recipients believe that the 2.8% COLA does not keep up with their cost of living.
- Among respondents over age 70, that figure rises to 82%.
- 61% of people who rely entirely or heavily on Social Security believe the COLA is not enough.
- 68% of all respondents say the increase helps very little or does not help at all with basic expenses.
All of the data comes from the same study, which included 2,000 Americans who receive Social Security. The survey was conducted through Pollfish, and the results were later adjusted by age and gender so the sample would better represent the national population.
COLA Tracks Inflation, but It Does Not Track Your Bills
The term cost-of-living adjustment gives the impression that Social Security checks every year to see how much more expensive life has become for retirees. The formula actually works in a much more specific way.
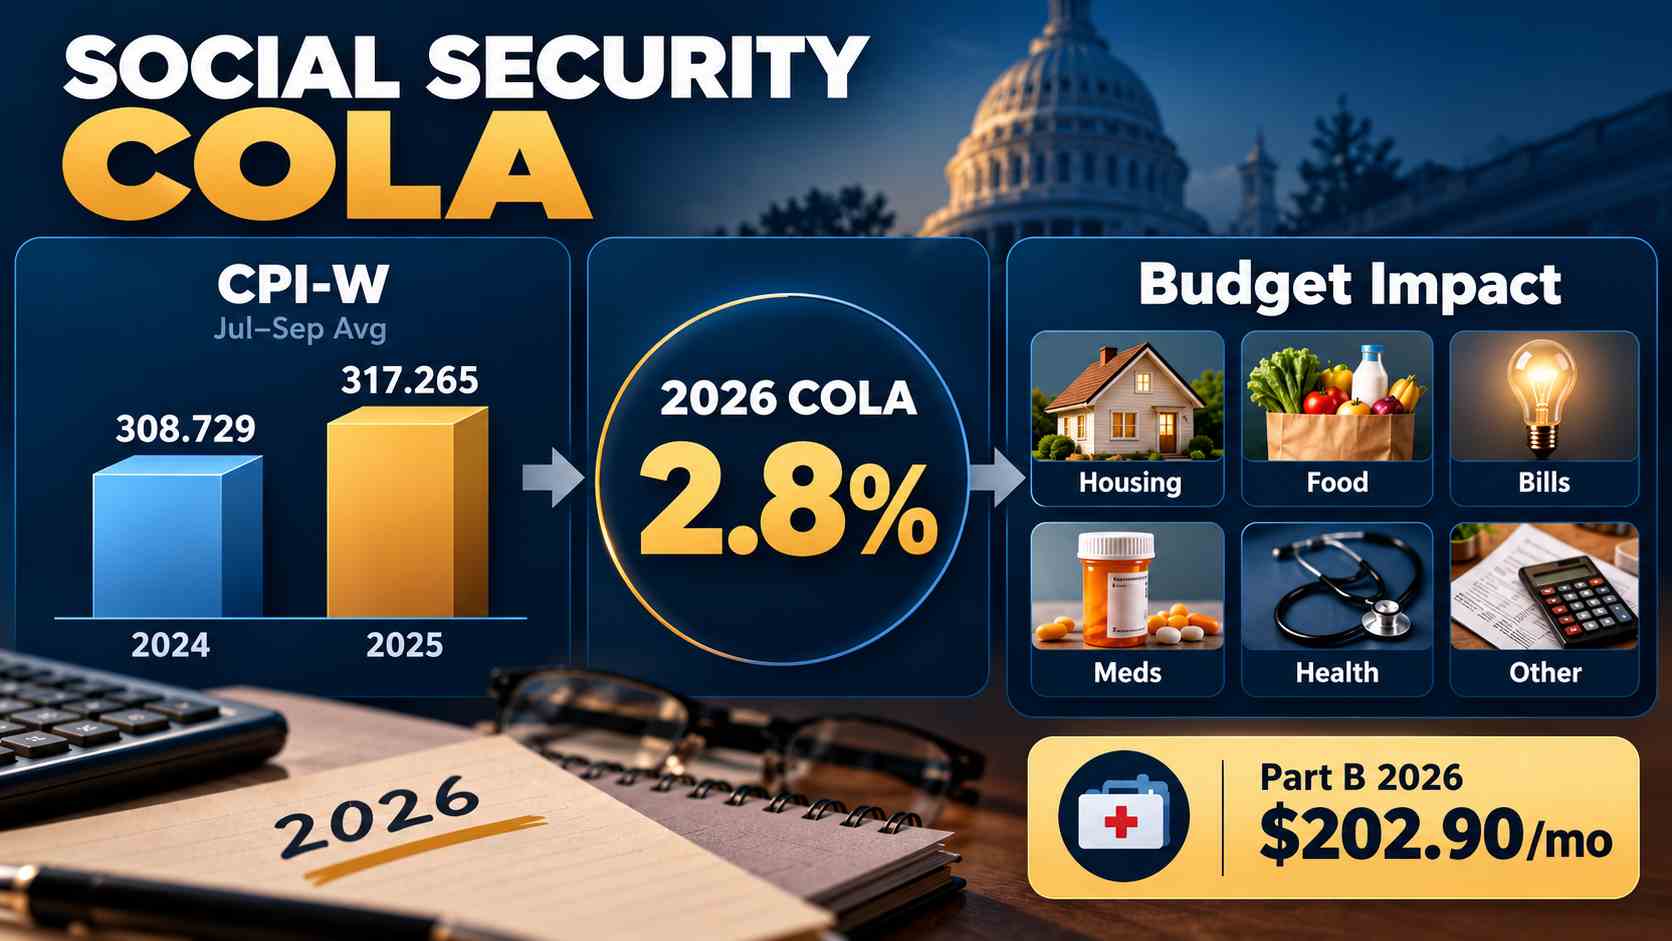
According to the Social Security Administration, the annual COLA is based on the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W. For the COLA that took effect at the start of 2026, the average CPI-W for July, August, and September 2025 was compared with the average for the same period in 2024. The index rose from 308.729 to 317.265. The difference, rounded under the formula set by law, was 2.8%.
There is no mathematical problem. COLA was calculated according to the formula required by law.
The problem starts when we try to translate that percentage into a real person’s budget.
A retiree does not buy CPI-W. A retiree pays for housing, food, electricity, insurance, medication, and health coverage. The share of income that goes toward each expense varies from person to person. Because of that, two people can receive exactly the same COLA and still end the year with very different changes in purchasing power.
A good example comes from Medicare. The standard Medicare Part B premium for 2026 is $202.90 per month. Since many recipients have the premium deducted directly from their Social Security check, an increase in that single expense can consume part of the COLA before the money even reaches them.
Our comparison makes the problem clearer. A Medicare premium can absorb part of the increase before a retiree receives the rest of the Social Security check.
COLA can accurately track the index required by law and still do a poor job of tracking the costs of a specific person.
For more on the household expenses that can outweigh a benefit increase,We explored a related problem in our guide to retirement costs many people overlook.
Maybe We Have Been Asking the Wrong Question
When a new COLA is announced, almost all the attention immediately goes to one question: is the increase large enough?
The survey raised a question worth asking: why does the same increase appear manageable to some retirees but inadequate to others?
The biggest clue appears among older recipients. Among respondents under age 70, 49% believe COLA does not keep up with the rise in their expenses. Among those age 70 or older, the figure jumps to 82%.
The study does not prove what causes such a large difference. It would be wrong to claim that health care costs, housing, or any other single expense is the only reason. The survey shows a pattern, not a causal relationship.
But the pattern is hard to ignore.
An even clearer difference appears when respondents are divided by how much they depend on Social Security. Among people who rely entirely or heavily on the benefit, 61% say COLA is not enough. Among those who depend on Social Security only a little or moderately, the figure is 42%.
That is a difference of 19 percentage points.
In other words, what matters is how many other financial cushions a retiree has when the cost of one bill rises faster than COLA.
The Same COLA Can Mean Something Very Different for Two Retirees
Let us take the simplest possible example.
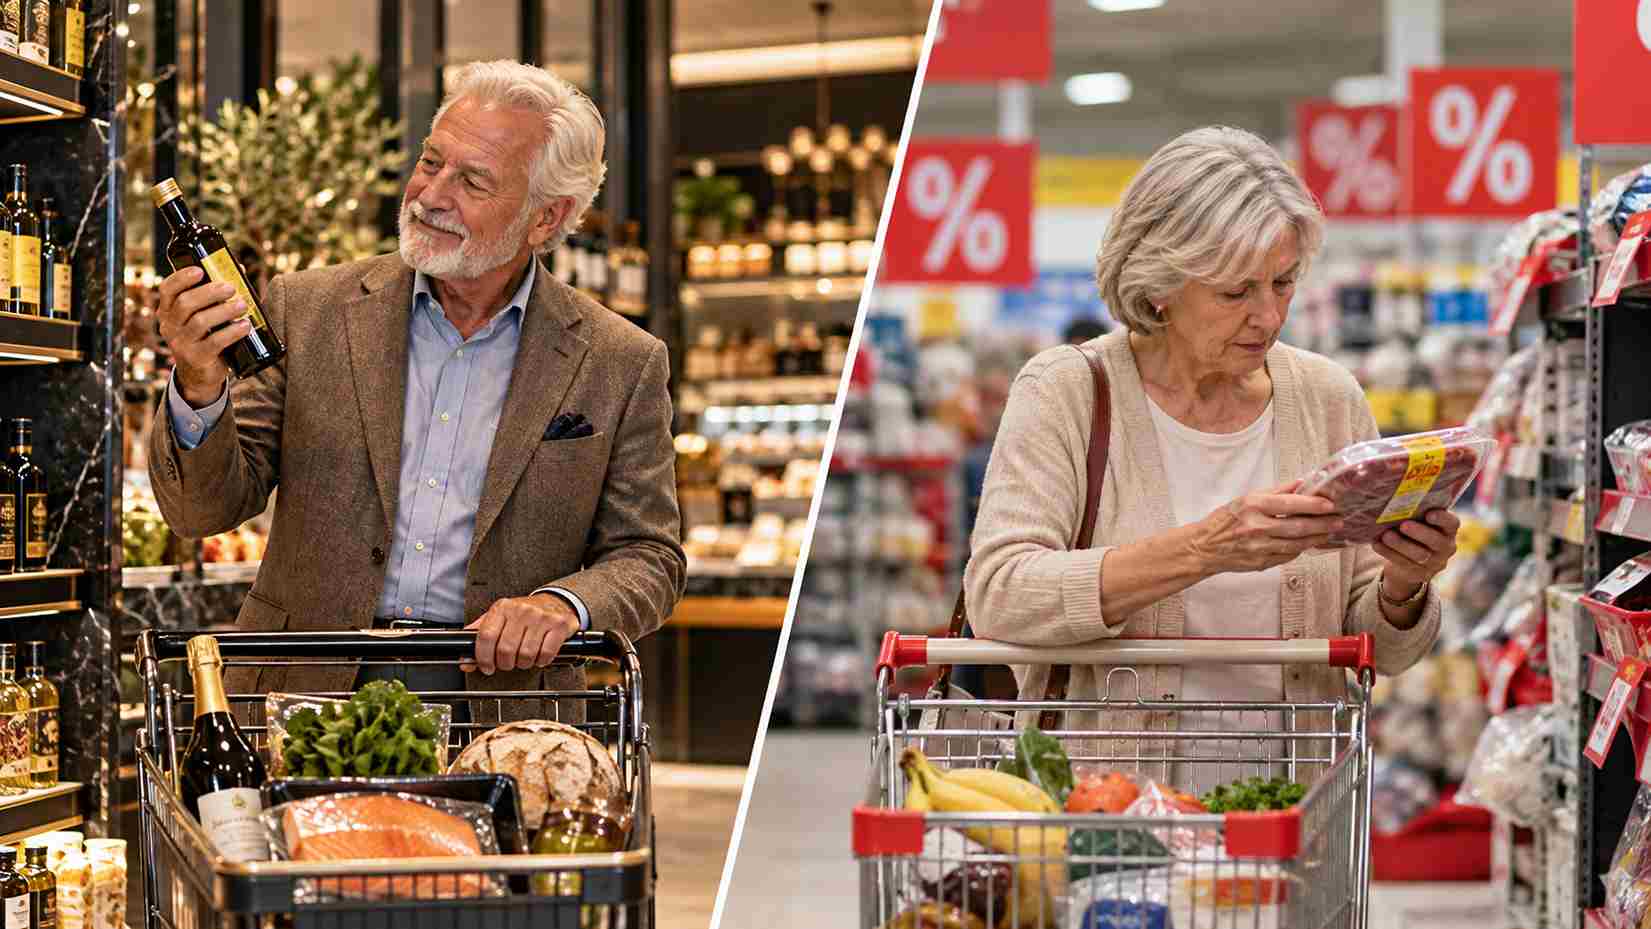
Two retirees each receive $2,000 per month from Social Security. A 2.8% COLA adds $56 to each check. By the end of January, both have received an increase of exactly the same size.
The first retiree has a paid-off home, an additional pension from a former employer, and an IRA account that he occasionally draws from. Social Security is an important part of his income, but it is not the only source. The second retiree lives almost entirely on Social Security. The same check has to cover housing, the Medicare premium, Medicare free, bills, and food.
Their increase is identical. Their financial situation is not.
A $56 increase tells you how much a check grew. To judge its value, you also need to know how much the household’s bills rose.
A Bigger COLA Sounds Like the Obvious Solution, but the Story Is Not That Simple
Respondents have a fairly clear view of how much larger the increase would need to be.
As many as 64% say COLA would need to be at least 6% to keep up with their cost of living. Nearly one-third, 31%, believe it would need to be at least 10%.
We would not treat those survey responses as proof that a 6% or 10% national COLA is the right solution. They describe what respondents believe their budgets need.
There is already a political debate around that exact issue. The Senior Citizens League and other organizations that represent older Americans have spent years calling for CPI-W to be replaced with an index that better reflects older Americans’ spending, such as CPI-E. The organization also points to several legislative proposals that would change the way COLA is calculated.
The debate received more attention during 2026 as estimates for the 2027 COLA rose; on October 14, SSA confirmed a 3.6% increase for 2027.
Yahoo Finance reported in September that pressure to change the formula itself was increasing again alongside expectations for a larger COLA.
The 2027 COLA is higher than the 2026 rate, but it is still one rate applied to tens of millions of people whose budgets have very little in common.
One Last Thought!
At first, a survey about COLA appears to be a simple story about the size of the increase. The more useful question is how much of that increase remains after regular bills are paid
Our review led to a more precise conclusion. COLA can follow the formula required by law and still fall short of the costs in your household.
The problem is that the national inflation rate and the cost of your own life are not the same thing.